The first question I ask a new client is not “how much do you make?” Instead, I ask, “where did last month’s money go?” Almost nobody can answer it. Still, that’s not a character flaw. Most people were simply never taught a budgeting system like the 50/30/20 rule, one that fits on the back of a napkin and still works in real life.
That’s the reason I keep coming back to this method. As an Accredited Financial Counselor, I have seen people try every budgeting approach out there: envelope systems, zero-based spreadsheets with 47 categories, and apps that ping them every time they buy a coffee. Many of those tools are good. However, the people who stick with a plan past month three usually share one thing. In short, their plan is simple enough to remember while they are standing in a checkout line.
The 50/30/20 rule is that kind of plan. Of course, it won’t fix every money problem, and it has real limits that I’ll be honest about below. Even so, for most households trying to get a clear picture of where their money goes, this is where I start.
Where the 50/30/20 Rule Came From
The rule didn’t come from a finance influencer. Instead, it was introduced by Elizabeth Warren, a former law professor who was part of the formation of the Consumer Financial Protection Bureau, in her book “All Your Worth: The Ultimate Lifetime Money Plan.” She wrote it with her daughter, Amelia Warren Tyagi, and the book came out in 2005.
What I appreciate about the origin story is the reasoning behind it. Warren had spent years studying why ordinary middle-class families ended up in bankruptcy. Surprisingly, it was not lattes and vacations. Rather, it was fixed costs (the mortgage, the car note, the insurance) swelling until any small shock knocked the household over. As a result, the rule was built as a guardrail against exactly that. The goal was a simple framework anyone could remember and use without spreadsheets or a finance degree.
I mention this because people sometimes treat the 50/30/20 rule like a trendy hack. In reality, it is a structural idea: keep your locked-in obligations at a level your income can actually carry, give yourself room to live, and protect your future on purpose.
How the 50/30/20 Rule Works
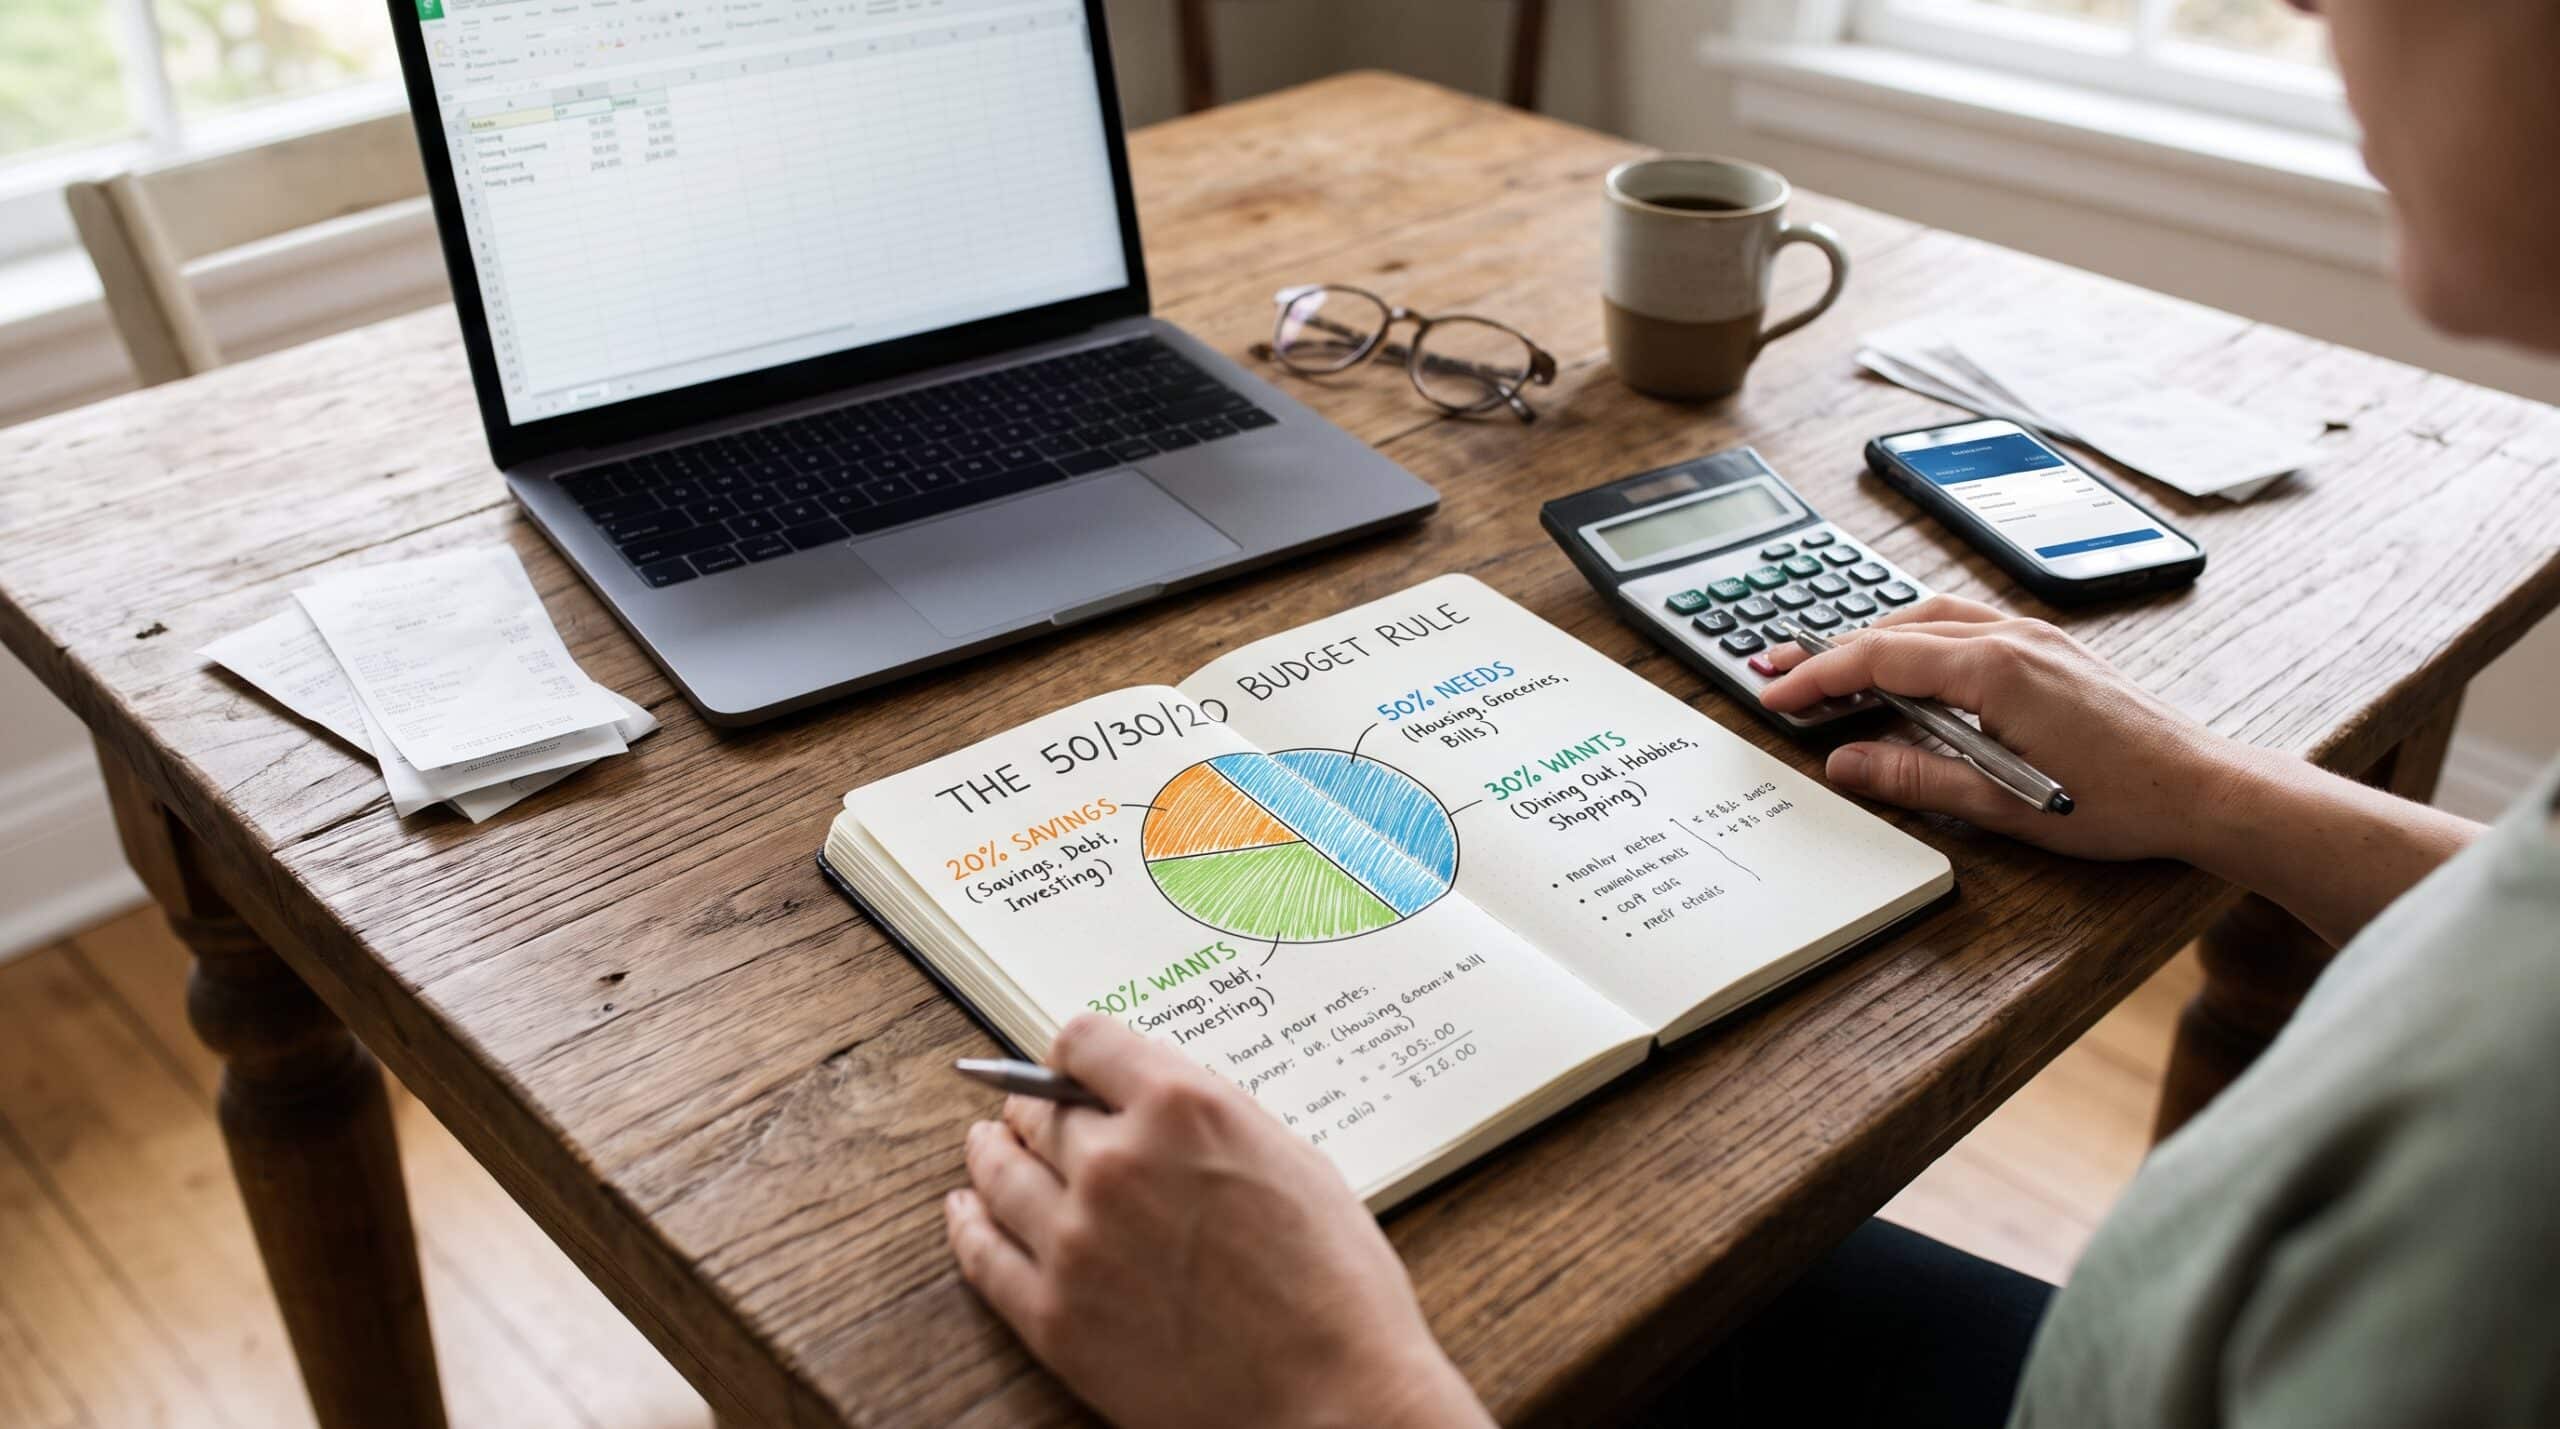
The method splits your after-tax income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt repayment. That’s the whole framework. Therefore, the real skill is in sorting your spending honestly.
Start With the Right Number
Before the percentages mean anything, you need the correct base. Specifically, the rule is built on your take-home pay, meaning your total income minus taxes.
Here’s a detail I see people miss all the time. If your employer pulls retirement contributions or health insurance premiums out of your paycheck before it hits your account, add those back in. After all, your 401(k) contribution is part of your 20%, while your health premium is part of your 50%. Otherwise, your percentages will look worse (or better) than they really are.
Needs: The 50 Percent
Needs are the things you’d have to pay even if you lost your job tomorrow. These include rent or mortgage, utilities, groceries (not restaurants), basic transportation to get to work, insurance, child care, and minimum payments on your debts.
The test I give clients is blunt: if you stopped paying this, would something bad happen fairly quickly? For instance, would you get an eviction notice, a shutoff, a repossession, or a ding on your credit report? If so, it’s a need.
Where people get tripped up, though, is the upgrade. Groceries are a need. On the other hand, premium groceries delivered to your door three times a week are partly a want. Similarly, a reliable car is a need, but the extra $200 a month for the trim level with heated seats is a want wearing a need’s clothing. You don’t have to feel guilty about that. Instead, just label it correctly.
Wants: The 30 Percent
Wants are everything that makes life enjoyable but isn’t required to keep it running. Examples include dining out, streaming services, hobbies, travel, gym memberships beyond the basics, and new clothes you’d like but don’t strictly need. In fact, Warren herself put things like cable and new clothes in the want category, even though they can feel like needs.
I’m protective of this bucket, because a lot of budgets fail when they treat fun like the enemy. When people cut wants to zero, they usually hold out for a few weeks and then blow up the whole plan in one weekend. That’s why thirty percent works as a permission slip. Essentially, it says you’re allowed to enjoy your money, as long as you know the limit.
Savings and Debt: The 20 Percent
This is the bucket that changes your future. It covers your emergency fund, retirement contributions, investing, and saving for big goals like a home down payment. In addition, it covers extra debt payments. Warren includes retirement plans, emergency funds, and any payment above the minimum on debt in this category.
So, if your credit card minimum is $90 and you pay $300, the $90 sits in needs and the other $210 counts toward your 20%.
I’ll say this plainly: if you only nail one bucket, make it this one. Even though the budget is written as 50/30/20, the whole point of the system is to put priority on the saving piece.
What the 50/30/20 Rule Looks Like in Real Numbers
Let’s use a composite example built from situations I see often. Call her Dana. She takes home $4,200 a month after taxes, and her paycheck already has a $250 retirement contribution and a $150 health premium pulled out. Consequently, her true base is $4,600.
Under the 50/30/20 rule:
- Needs (50%): $2,300
- Wants (30%): $1,380
- Savings and debt (20%): $920
Next, we compare that to her real spending. Rent is $1,450, while utilities and phone run $260. On top of that, groceries are $480, her car payment and insurance total $520, her health premium is $150, and the minimum on a credit card is $80. Altogether, that’s $2,940 in needs, or about 64%.
In other words, Dana is over in needs by $640. That’s very common, and it isn’t the end of the world. What matters most is what she does next. In her case, the car was the pressure point. By refinancing at a lower rate and dropping a coverage add-on she didn’t use, she freed up about $110. She also realized her $480 grocery line had about $90 of convenience food that honestly belonged in wants. As a result, her needs dropped closer to 60%, and we set a target to work toward 50% over time rather than forcing it overnight.
Meanwhile, her retirement contribution of $250 plus a new $150 automatic transfer to savings got her to $400 in the 20% bucket. Admittedly, that’s not $920 yet. Still, it’s up from basically nothing in savings outside her 401(k), and that’s progress you can build on.
How to Set Up the 50/30/20 Rule Step by Step
This is the process I use in sessions, and you can do it yourself in about an hour.
1. Pull Three Months of Statements
One month lies. After all, you might have had a birthday, a car repair, or a slow week. Three months, by contrast, gives a more honest average. To begin, go through your bank and credit card statements and list every transaction, or export them into a spreadsheet.
2. Calculate Your True Take-Home Pay
First, add up what lands in your account. Then add back anything pulled from your paycheck for retirement or health coverage. If your income varies, however, use your lowest month from the past year as your baseline. I’ll explain why in the section on irregular income.
3. Sort Every Expense Into Three Buckets
Needs, wants, savings and debt: there’s no fourth category called “other.” If you can’t decide, simply ask the test question from earlier: what happens if I stop paying this? Above all, be honest with yourself, not harsh.
Fortunately, the Consumer Financial Protection Bureau offers free tools to help with this, including an income tracker, a spending tracker, a bill calendar, and a budget worksheet that pulls everything together in one place.
4. Compare Your Real Percentages to the Target
This is the moment of truth. Most people find needs running higher than 50% and savings running far below 20%. Again, that’s normal. In this step, you’re getting a diagnosis, not a grade.
5. Make One or Two Changes, Not Ten
Pick the biggest lever. Renters might find it in a roommate or a move at lease renewal. In many households, on the other hand, the car is the real culprit. Others discover subscriptions quietly eating $150 a month. While small fixes add up, the large fixed costs are where the real room comes from. For more ideas, see these ways to save money every month.
6. Automate the 20% First
Set up an automatic transfer on payday, before you have a chance to spend. Notably, the CFPB points out that automatic recurring transfers are often one of the easiest ways to build savings, especially when the money moves into a separate account before it reaches checking. That’s why I tell clients to pay their future self the way they pay their landlord: first, and without debate.
7. Check In Monthly
Finally, set aside fifteen minutes once a month. Look at the three totals. Did the wants bucket overflow? Did a need creep up? If so, adjust and move on. If that review keeps slipping off your calendar, these tips on how to stop procrastinating can help. Ultimately, a budget is a living thing, not a document you write once and frame.
Your Emergency Fund Under the 50/30/20 Rule
Inside the 20% bucket, I usually ask clients to build a starter emergency fund before they get aggressive with investing or extra debt payments. Without it, the next car repair goes on a credit card and undoes months of progress.
The numbers explain why. In the Federal Reserve’s household survey covering 2024, 63 percent of adults said they would cover a hypothetical $400 emergency expense using only cash or its equivalent, unchanged from 2022 and 2023 but down from a high of 68 percent in 2021. Put another way, more than a third of adults couldn’t handle a modest surprise bill with cash on hand.
So how big should the fund eventually be? Generally, saving three to six months of essential expenses is the common recommendation, although individual circumstances may call for more or less. The CFPB, meanwhile, takes a practical angle. It suggests you think about the most common unexpected expenses you’ve had before and what they cost, then use that to set a goal.
My usual sequence goes like this. First, save one month of needs. Second, capture any employer retirement match, since that’s free money. Third, attack high-interest debt. After that, keep growing the emergency fund toward three to six months.
Where the 50/30/20 Rule Bends (and Sometimes Breaks)
I’d be doing you a disservice if I pretended this rule fits everyone. It doesn’t. Here’s where I adjust it with clients.
Lower Incomes and High-Cost Areas
If you live in an expensive city or earn a modest income, housing alone can eat 40% of your take-home pay. In that situation, the rule may be difficult or flatly unrealistic. Needs at 60% or even 70% is therefore not a failure. It’s just math. Instead of giving up, we shrink wants and protect whatever savings we can, even if it starts at 5%. Adding income helps too, and some of these side hustle ideas can be started in a weekend.
Using the 50/30/20 Rule With Irregular or Gig Income
Freelancers, commission earners, seasonal workers, and rideshare drivers often struggle with any percentage system, since their income changes month to month. My fix is straightforward. Build your needs budget around your lowest typical month, and then treat anything above that as a bonus to split between savings and wants. In addition, a separate tax savings account is nonnegotiable for the self-employed.
Heavy Debt
If you’re carrying credit cards at 25% interest, 20% toward savings and debt might not be enough to make a dent. In other words, the rule may not put enough priority on debt repayment for people with substantial balances. For those clients, I often temporarily shrink wants to 15 or 20% and push the difference toward debt until the high-interest balances are gone.
Higher Earners
The opposite problem exists too. Someone earning a high income who only saves 20% may be underselling their future. So if your needs come in at 35%, don’t let lifestyle inflation quietly absorb the extra 15%. Instead, redirect some of it to savings.
Popular Variations of the 50/30/20 Rule
Since the original framework is flexible, a few variations have become common.
The 60/20/20 split gives needs 60%, wants 20%, and savings 20%. As a result, it’s often more realistic in high-cost housing markets.
With 70/20/10, on the other hand, 70% goes to essentials, 20% to savings, and 10% to debt repayment.
Lastly, the 80/20 approach has you save 20% first and then spend the remaining 80% however you like without tracking categories. It’s great for people who hate budgeting but are disciplined about automation.
Depending on your situation, your percentages might look more like 50/20/30, 40/10/50, or another mix entirely. That’s fine, because the percentages are a target, not a law. What matters is that you choose your split intentionally instead of letting your spending choose it for you.
Common 50/30/20 Rule Mistakes I See Over and Over
After years of sitting across the table from people working through this, I’ve noticed a few patterns come up again and again.
Using gross income. Your salary on paper isn’t what you spend, so start from take-home pay with paycheck deductions added back.
Hiding wants inside needs. Think of the phone plan with unlimited everything, the bigger apartment, or the second streaming bundle. Unless you label honestly, the math stops meaning anything.
Forgetting irregular expenses. Car registration, annual subscriptions, holiday gifts, and school supplies all count. To handle them, divide the yearly total by twelve and budget for it monthly. Otherwise, these show up as “emergencies” that aren’t really emergencies.
Treating 30% as a minimum. The wants bucket is a ceiling, not a spending target. So if you only use 22%, move the difference to savings.
Quitting after one bad month. Everyone overspends sometimes. Even so, one rough month doesn’t break the system, but quitting does.
Not talking to a partner. If you share finances, both people need to agree on what counts as a need. Honestly, I’ve seen more budgets fall apart over whether takeout counts as food than over any actual shortfall.
Why the 50/30/20 Rule Still Works
I’ve worked with people who earn far more than average and still live paycheck to paycheck. At the same time, I’ve worked with people on tight incomes who built real savings. The difference is rarely the size of the paycheck. Rather, it’s whether they have a structure and actually use it.
The 50/30/20 rule gives you that structure without burying you in detail. Instead of thirty numbers, you track three. Along the way, you give yourself permission to enjoy your money. Most importantly, your future gets protected automatically.
So start with your real numbers, and expect them to look messy. Then make one change this month and one more next month. Six months from now, you’ll know exactly where your money goes, and that’s when the real progress begins.
Frequently Asked Questions About the 50/30/20 Rule
What is the 50/30/20 rule in simple terms?
It’s a budgeting guideline that divides your after-tax income three ways: 50% for needs, 30% for wants, and 20% for savings and extra debt payments. It was popularized by Elizabeth Warren and Amelia Warren Tyagi in their book on household finances. For a plain overview, see Chase’s guide to the 50/30/20 budget rule.
Is the 50/30/20 rule based on gross or net income?
It’s based on net income, meaning your take-home pay after taxes. However, if your employer deducts retirement contributions or health premiums before you’re paid, add those back so they count in the right bucket. SoFi’s explainer on the 50/30/20 budget walks through this as well.
Does the 50/30/20 rule include retirement savings?
Yes. Retirement contributions belong in the 20% savings and debt bucket, along with your emergency fund and payments above the minimum on any debt. CollegeAve’s breakdown of the rule covers this question directly.
What if my needs are more than 50% under the 50/30/20 rule?
That’s very common, especially in high-cost housing markets. In that case, use a variation like 60/20/20, reduce wants first, and look for one large fixed cost to bring down over time. InCharge Debt Solutions’ guide also discusses when the rule may not fit lower incomes.
Should I pay off debt or build an emergency fund first?
In most cases, build a small starter emergency fund first, so a surprise bill doesn’t send you back to the credit card. After that, focus extra money on high-interest debt while you keep growing savings. Bankrate’s emergency fund guide explains how to size your fund.
Does the 50/30/20 rule work with irregular income?
It can, with a few adjustments. Specifically, base your needs budget on your lowest typical month and send any extra income to savings and wants. The CFPB’s free budgeting tools and worksheets are also helpful for tracking variable income.
How often should I review my 50/30/20 rule budget?
Once a month is enough for most people. A quick check of your three totals lets you catch drift before it becomes a problem. In addition, a deeper review once a year or after any major life change keeps your percentages realistic.
References
- The 50/30/20 Rule for Budgeting, InCharge Debt Solutions
- What Is the 50/30/20 Budget Rule?, Fox Business
- 50/30/20 Budget Rule, CollegeAve
- What Is the 50/30/20 Rule? A Simple Budget Method Explained, Acorns
- The 50/30/20 Budget Rule, Chase
- 50/30/20 Budget Rule: What It Is and Tips on Using It, SoFi
- What Is the 50 30 20 Rule?, Raisin UK
- 50/30/20 Rule and Alternatives, WallStreetMojo
- Federal Reserve Board Issues Economic Well-Being of U.S. Households in 2024 Report, Federal Reserve
- Survey of Household Economics and Decisionmaking: Unexpected Expenses Data, Federal Reserve
- Federal Reserve Publishes Household Economic Well-Being Report, NRMLA
- How to Start and Build an Emergency Fund, Bankrate
- What Is an Emergency Fund?, ClearValue Lending
- An Essential Guide to Building an Emergency Fund, Consumer Financial Protection Bureau
- CFPB Offers Guide to Setting Up an Emergency Fund, The League Insider
- Tools and Resources to Use With the People You Serve, Consumer Financial Protection Bureau